How to Calculate TCO and ROI in Fastener Procurement: Moving from Unit Price Comparison to Total Cost Decision-Making

Daniel
With experience in fastener manufacturing and export sales, we specialize in bolts, nuts, screws, self-drilling screws, fully threaded rods, and customized fastening solutions for construction, machinery, automotive, and industrial applications.
Why a low purchase unit price does not equal low procurement cost
In fastener procurement, the most common dilemma is this: when several suppliers' quotations are laid out side by side, the one with the lowest unit price looks the most competitive, and the procurement department easily makes decisions based on that. But the problems only gradually emerge after actual use—batch quality fluctuations cause frequent assembly line adjustments, delivery delays force the production line to reschedule at the last minute, inventory buildup ties up large amounts of capital, and even a singlescrewwith stripped threads or breakage triggers rework of an entire batch of products. These subsequent expenses are often completely invisible on that initial quotation.
Bolts,nuts,studsand other fasteners usually have low unit prices, with per-piece price differences of perhaps only a few cents to a few dimes, but they are used in enormous quantities and across many application stages. From incoming inspection and warehouse management to the assembly floor and after-sales maintenance, tiny differences at each stage are magnified by the huge usage volume. Anutthat is two cents cheaper per unit, if the annual usage is several million pieces and it also brings a higher defect rate and more frequent line stoppages, may end up completely reversing the final cost calculation.
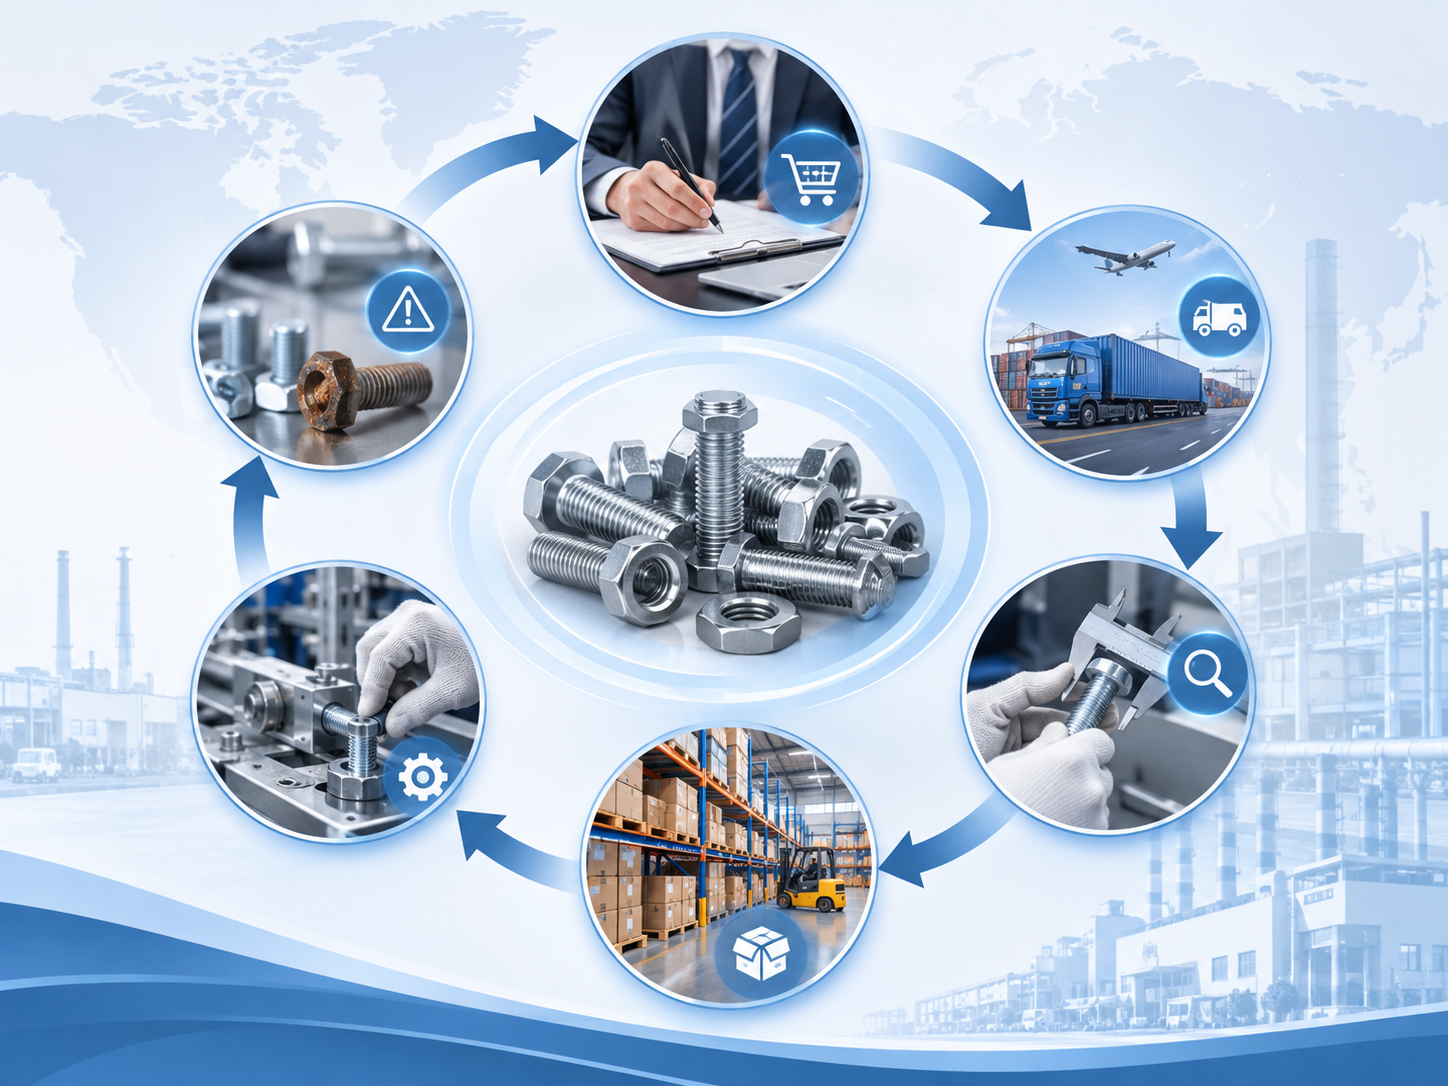
Therefore, the logic of procurement decisions should shift from "comparing unit prices" to "comparing total cost of ownership (TCO)," and combine it with return on investment (ROI) to judge whether a given optimization plan is worth investing in. Unit price is only the starting point of the cost chain, not the end point.
Fastener procurement TCO: the complete cost chain from quotation to use
TCO (Total Cost of Ownership) refers to all costs an enterprise bears for procuring, receiving, storing, using, and managing fasteners within an agreed period. It is not a precise financial accounting item, but a decision-making tool that helps procurement teams see the full picture.
A practical basic formula is:
TCO = procurement cost + logistics and tariff cost + inspection and management cost + inventory cost + quality loss cost + downtime and maintenance cost
Before starting the calculation, the boundaries must be clearly defined; otherwise, different plans cannot be compared horizontally. Items that need to be clarified include: product scope (a single specification or the entire category), statistical period (one year or three years), currency and exchange rate basis, annual purchase volume, statistical basis for losses and nonconforming products, and whether indirect losses such as equipment downtime and customer claims are included. If the boundaries are unclear, the calculation results will be distorted.
At the same time, beware of double counting. For example, if the labor cost of rework has already been included in quality losses, it should not be counted again in downtime losses; if expedited shipping costs have already been included in logistics costs, they should not be counted again in delivery delay losses. It is recommended to note the data source for each cost item in the calculation table to avoid the same expense being counted twice.
Six types of hidden costs that are easily overlooked
Quotations usually reflect only the product unit price, while what really widens the TCO gap is often the following six types of hidden costs.
- Procurement and order processing costs:The labor time consumed by inquiry, price comparison, order placement, expediting, and reconciliation, as well as the multiple procurement management costs caused by suppliers' minimum order quantities or partial shipments. The more suppliers there are and the more fragmented the batches, the higher this cost.
- Logistics and delivery costs:Transportation, packaging, expedited delivery, import customs clearance fees, and additional expenses caused by delayed delivery. Suppliers with unstable delivery times often force buyers to pay expedited freight or maintain higher safety stock.
- Incoming inspection and quality management costs:Sampling inspection, re-inspection, batch traceability, handling of nonconforming products, and supplier audit costs. For suppliers with large quality fluctuations, inspection frequency and inspection manpower will both increase significantly.
- Inventory and capital occupation costs:Safety stock, warehouse space, inventory counting manpower, losses from obsolete and scrapped stock, and the opportunity cost of capital tied up in inventory. If low-price, large-volume purchases cannot be consumed, inventory costs will quietly eat up the price difference.
- Assembly and on-site use costs:Installation labor hours, tool wear, incorrect assembly, thread stripping, loosening, breakage, and the cost of replacement. Poor dimensional accuracy or unstable thread quality inscrewswill directly slow down the assembly takt time.
- Quality incident and downtime costs:Losses caused by product rework, customer claims, production line downtime, and delivery delays. These costs are the hardest to see from a quotation, but once they occur, the amount often far exceeds the annual procurement price difference.
Different fasteners and application scenarios also have different cost structures
There are many categories of fasteners, and the cost structures of different products differ significantly, so the same set of weights cannot be used to measure all procurement items.
Takinghex bolts,flange bolts,studsandnutsas examples, focus should be placed on specification matching, assembly efficiency, connection reliability, and replacement difficulty. Flange bolts have an integrated flange surface, which can reduce the use of washers and assembly steps, saving labor hours in batch assembly scenarios; while ordinary hex bolts have a lower unit price, if additional washers are required, the overall assembly cost may not be better.
When evaluatingstainless steel fasteners, carbon steel products, and surface treatment options, corrosion resistance requirements, service life, and maintenance frequency should be included in the lifecycle cost. In outdoor or humid environments, low-priced carbon steel parts may rust within one or two years, and the replacement and maintenance costs far exceed the original procurement price difference; whilestainless steel fasteners, although higher in unit price, require less frequent maintenance, making the long-term TCO more controllable.
For products such ashigh-strength bolts,hot-dip galvanized bolts,lock nuts, the material, performance, and inspection costs should be evaluated according to operating condition requirements. A high strength grade means stricter material control and testing requirements, the hot-dip galvanizing process affects the corrosion resistance years, and the locking structure relates to anti-loosening reliability under vibration environments; all of these should be factored into the cost model.
Forcustom socket head cap screws,Custom fasteners for special-shaped partsornon-standard fastener machining, additional costs such as mold fees, prototyping fees, certification fees, minimum order quantities, and subsequent design change costs must also be calculated separately. The hidden costs of custom parts tend to be concentrated in upfront investment and change risks, and should be listed as separate line items during cost estimation.
In actual assembly, products such as DIN 963 slotted countersunk machine screws feature a countersunk design, slotted drive, and metric threads, allowing them to sink into the workpiece surface for a flush assembly; they are commonly used in equipment panels, furniture hardware, and general assembly scenarios. DIN 965 cross-recessed countersunk machine screws, by contrast, use a cross recess drive, which provides more stable torque transmission, making them suitable for electrical equipment, furniture, and panel assembly where assembly efficiency matters. For these two types ofmachine screwswhen selecting, in addition to unit price, the impact of drive type on assembly labor hours and tool wear should also be compared—the efficiency difference between slotted and cross recess in batch assembly will directly show up in on-site usage costs.
Reusable TCO and ROI calculation model
Below is a calculation framework that can be applied directly; enterprises can adjust the parameters according to their own data.
Annual TCO model
Annual TCO = annual procurement amount + annual logistics and tariffs + inspection and management costs + inventory holding costs + quality losses + downtime losses
Among these, inventory holding cost can be estimated as "average inventory value × annual holding cost rate." The holding cost rate usually includes capital cost, warehousing, insurance, and shrinkage; the specific value should be confirmed by the company's finance or supply chain team and should not be directly copied from external rules of thumb.
Annual quality loss can be calculated as "number of nonconforming items × unit rework or scrap cost," plus verifiable claims, re-inspection, and line stoppage losses. All indirect losses should be based on historical records rather than subjective estimates.
ROI and payback period model
ROI = (annual TCO before optimization − annual TCO after optimization − solution implementation cost) ÷ solution implementation cost × 100%
The payback period can be calculated as "one-time implementation investment ÷ annual net savings." If annual net savings are not positive, it means the solution is not viable under the current assumptions; the assumptions should be rechecked or the solution adjusted rather than forcing it through.
Suggested fields for the calculation sheet
- Product specifications and category
- Supplier name and location
- Unit price and annual usage
- Inspection nonconformance rate
- Inventory days and average inventory value
- Unit rework cost
- On-time delivery rate
- Solution implementation costs (molds, certification, systems, training, etc.)
Example: How to compare a low-price quote with a low-TCO solution
The following is a hypothetical case, intended only to demonstrate the calculation logic. All data are assumptions and do not represent any real company or supplier.
Assume a company needs a certain specification annuallybolts1 million units. Option A has a unit price of 0.10 yuan, and Option B has a unit price of 0.12 yuan. Option A has a defect rate of 2%, while Option B has 0.3%; Option A has an on-time delivery rate of 90%, while Option B has 98%; Option A requires 45 days of safety stock, while Option B requires 20 days.
- Procurement cost:Option A is 100,000 yuan, and Option B is 120,000 yuan.
- Quality loss:Calculated at a rework cost of 1.5 yuan per unit, Option A has 20,000 defective units, with a loss of about 30,000 yuan; Option B has 3,000 defective units, with a loss of about 4,500 yuan.
- Inventory holding cost:Estimated based on average inventory value and the annual holding cost rate, Option A has significantly higher holding costs than Option B because its inventory days are longer.
- Downtime loss:Option A has a lower on-time delivery rate. Converted based on historical line-stop records, it may incur additional losses each year; for Option B, this item is close to zero.
After adding up the above items, although Option A saves 20,000 yuan on the procurement unit price, quality losses and inventory costs may already offset or even exceed this price difference. At this point, applying the ROI formula can determine whether switching to Option B is worthwhile and how long the payback period is.
Further sensitivity analysis can test the impact on ROI of fluctuations in procurement volume, changes in defect rate, adjustments to the inventory holding cost rate, and fluctuations in downtime costs. If the conclusion remains stable within a reasonable range, the option's credibility is higher; if the conclusion is extremely sensitive to a certain parameter, data should be supplemented before making a decision.
How to verify the true comprehensive value of fastener suppliers
Beyond unit price, a supplier's true value is reflected in its quality system, batch consistency, traceability, delivery performance, technical support, and speed of exception response. These dimensions can be cross-confirmed through supplier audits, historical performance data, and sample verification.
It is equally important to verify supply and manufacturing capabilities by category. For example, when examininghex bolt manufacturersit is necessary to confirm their specification coverage and heat treatment capabilities; when selectingflange bolt suppliersfocus on the forming precision of the flange surface; when looking forheavy hex nut manufacturersorlock nut suppliersit is necessary to check material grades and anti-loosening performance test reports. Forstainless steel fastener manufacturersmaterial certificates and salt spray test data are basic thresholds.
For different categories, the verification focus also differs:carriage bolt factoriesneed to confirm the consistency of head forming and neck dimensions;self-tapping screw manufacturersandself-drilling screw suppliersattention should be paid to edge machining precision, carburized layer quality, and drilling performance. The specification range, inspection capability, and capacity match should all be included in the evaluation table.
involvingexport of inch-standard bolts,fastener export suppliersorfastener OEM contract manufacturing, it is also necessary to verify applicable standards, inspection documents, packaging requirements, tariffs, and cross-border delivery arrangements. Non-compliance with standards or missing documents may cause the entire shipment to be held up, and such risk costs should be included in the TCO in advance.
In addition,expansion bolt wholesale,machine screw wholesale,custom bolt wholesaleand other different procurement needs should be incorporated into a unified TCO evaluation table, avoiding each product category acting separately and comparing only quotations. Only a unified evaluation basis can allow different categories offastener suppliersto be compared on the same scale.
Implementation recommendations: from small-scale pilots to procurement standardization
The TCO model does not need to cover all categories at once; doing so may instead easily become a mere formality due to insufficient data. A more pragmatic approach is to proceed step by step.
- Select pilots:First select fastener categories with high annual procurement value, traceable quality losses, or obvious shutdown impact for TCO trial calculations, such as high-usagescrewsorboltsat key connection points.
- Unify definitions:Invite procurement, quality, production, warehousing, and finance teams to jointly confirm cost items and data sources, ensuring that all departments use the same set of definitions.
- Small-batch validation:Through sample validation and small-batch trials, compare actual assembly efficiency, quality performance, and delivery stability, and use real data to revise model assumptions.
- Establish a review mechanism:Regularly update defect rates, on-time delivery rates, inventory turnover, and annual savings data to turn supplier performance from a "one-time evaluation" into "continuous tracking."
Ultimately, good procurement is not simply about buying something cheaperbolts, but about reducing total lifecycle costs through verifiable quality and stable supply capacity. When the procurement team can speak in terms of TCO and ROI, negotiations with suppliers will also shift from "cutting a few more cents" to "how to jointly reduce waste"—this is where the true value of fastener procurement lies.

